

Author: Honda Van Nuys Team
Deciding whether to finance or lease a fuel-efficient Civic for commuting down Van Nuys Boulevard or a spacious CR-V for errands in Panorama City is a major choice. The right path depends on your daily habits, from running quick trips around Reseda and North Hills to tackling longer highway commutes toward North Hollywood, Sherman Oaks, and Encino.
At Honda Van Nuys, we value our long-standing presence in the community as a reliable, long-term automotive partner for drivers in Van Nuys, CA, and nearby areas. We explicitly highlight our expertise in servicing and maintaining Honda vehicles, emphasizing our deep local knowledge and trusted experience to keep your car running smoothly.
Key Takeaways (TL; DR)
Navigating your auto loan or lease options does not have to feel overwhelming. Whether you are financing a fuel-efficient 2027 Honda Civic for your daily commute down Victory Boulevard or leasing a spacious CR-V Hybrid for family errands around Sherman Oaks, understanding the basics puts you in control. Typical financing terms run between 36 and 72 months, and securing a lower annual percentage rate (APR) directly reduces your total out-of-pocket expense. That means a better grasp of your budget translates into real savings, freeing up your funds for everyday life in the San Fernando Valley.
- Credit History Matters: Your current credit score is the main driver behind the interest rates you will be offered. A higher tier—such as a score above 720—usually unlocks the most competitive terms, lowering the total amount you pay over the life of the loan.
- Honda Financial Services (HFS): Leveraging Honda’s in-house financing often provides access to exclusive promotional rates and streamlined approvals. You can even submit an application online to see what you qualify for before stepping foot on the lot.
- Buying vs. Leasing: Financing means you are building equity to eventually own your vehicle outright. Conversely, a standard 36-month lease generally comes with lower monthly payments since you are only covering the vehicle's depreciation, making it an easy way to get the newest safety tech for navigating stop-and-go traffic on the 405 freeway.
- Flexible Lease-End Routes: When a lease concludes, you are not locked into a single path. You can choose to buy the car at its predetermined residual value, hand the keys back, or seamlessly start a new lease on the latest model.
- Targeted Savings Programs: Eligible shoppers can take advantage of specific Honda incentives, such as the College Graduate Bonus or Military Appreciation offers, which help minimize initial drive-off costs.
- Upfront Preparation: Bringing the right paperwork—like recent pay stubs and proof of residence—speeds up the whole transaction. Checking your credit report and setting a strict monthly budget before cruising down Van Nuys Boulevard ensures you shop with confidence.
How Auto Financing Works for Honda Buyers
When you finance a vehicle, you borrow the purchase price from a lender—such as a local credit union or Honda Financial Services—and pay it back plus interest over a set schedule. This timeline, known as your loan term, typically ranges from 36 to 72 months depending on the monthly payment you want to target. What this means for Van Nuys drivers is that you can secure the keys to a fuel-efficient 2027 Honda Civic for daily, stop-and-go commutes down Victory Boulevard without having to cover the entire cost upfront.
Unlike leasing, choosing to finance means every monthly payment builds equity—the actual cash value you hold in the vehicle. For example, if you finance a spacious 2026 Honda Pilot to haul groceries from the Panorama Mall and gear for weekend trips up to the San Gabriel Mountains, you are steadily paying toward full ownership. Once your loan is completely satisfied, the lender transfers the title directly into your name. Because financing comes with zero mileage limits, this path makes the most sense if you regularly cross the San Fernando Valley and want a reliable asset to keep for the long haul.
Understanding Honda Financial Services

When securing a loan or lease in the San Fernando Valley, working with Honda Financial Services streamlines the purchasing process directly at the point of sale. For drivers shopping near the Van Nuys Government Center or commuting down Van Nuys Boulevard, securing factory-backed financing means keeping monthly vehicle expenses predictable. Instead of juggling third-party lenders, this official captive lender consolidates your paperwork, giving you direct access to targeted APR specials and lease structures designed exclusively for new and certified pre-owned Honda vehicles.
The smartest way to begin is by completing an online pre-approval application, which allows you to gauge your exact buying power before stepping onto the lot. Once submitted, the application system evaluates your income, debt-to-income ratio, and credit history to determine your eligibility, meaning final interest rates and promotional offers will vary by credit. Whether you are looking to finance a fuel-efficient 2027 Honda CR-V Hybrid for grocery runs to Panorama Mall or lease a 2026 Honda Accord for comfortable daily trips to Sherman Oaks, your credit profile dictates the terms available to you.
Locking in a competitive APR through manufacturer financing makes a tangible financial difference over the lifespan of a vehicle loan. For example, shaving just two percentage points off a standard 60-month term noticeably reduces the total interest paid, freeing up more of your budget for everyday California living expenses. Because Honda frequently introduces loyalty bonuses for returning lessees and buyers, utilizing their official financing arm often yields further financial incentives when it is time to upgrade your ride.
How Leasing a Honda Actually Works
When you lease a vehicle like a 2027 Honda Civic Hybrid, you are paying strictly for the portion of the car's lifespan that you utilize. Instead of financing the full purchase price, your monthly payments cover the vehicle's expected depreciation. The math comes down to the difference between the car's initial capitalized cost and its residual value—the amount it is projected to be worth when your contract ends. Alongside depreciation, your payment includes standard fees, taxes, and a rent charge dictated by a money factor, which functions similarly to an interest rate. If your daily routine involves navigating stop-and-go traffic down Sepulveda Boulevard or running errands near Westfield Fashion Square, understanding this structure clarifies exactly how your transportation budget is applied.
Typical Honda lease terms generally run between 24 and 36 months. Because this duration typically aligns with the standard New Honda 3-Year/36,000-Mile Limited Warranty, major mechanical components remain covered while the vehicle is in your possession. What this means for Van Nuys drivers is a predictable, fixed-term arrangement. Once the lease matures, you return the vehicle without having to manage resale logistics or trade-in negotiations. Whether you use a CR-V for daily commutes or weekend trips toward the San Gabriel Mountains, a lease provides a defined timeline based solely on the car's projected depreciation.
Navigating Your Honda Lease-End Options in the Valley
What this means for Van Nuys drivers is having the freedom to plan your next move well before your contract actually expires, helping you avoid surprise fees and smoothly transition your daily commute. Whether you have kept your Honda Civic well under its annual mileage limit navigating local routes like Van Nuys Boulevard, or you are ready to swap into a more spacious CR-V for grocery runs to the Panorama Mall, starting the process about 60 to 90 days before your lease maturity date ensures you have time to weigh these three straightforward paths.
- Buy Out Your Current Honda: You can purchase your leased vehicle for the predetermined residual value locked into your original agreement. For instance, if you have driven more miles than expected on cross-Valley trips via the 405 freeway, buying the car outright means you will not have to worry about paying excess mileage penalties.
- Upgrade to a New Honda: Turn in your current vehicle and start a fresh lease or finance contract on a newer model. Swapping an older gas-powered sedan for a new Accord Hybrid is a practical step for residents looking to adopt modern technology and lower fuel costs in busy stop-and-go traffic.
- Return Your Vehicle: You also have the option to simply hand in the keys and conclude your contract. To do this efficiently, schedule a complimentary end-of-lease inspection to check for excess wear and tear—like minor door dings from tight parking spaces—allowing you time to address any concerns before the final turn-in date.
Deciding Between Financing and Leasing Your Next Honda

The main difference comes down to ownership. Financing a Honda CR-V means the title transfers to you after your final payment. Leasing operates like a long-term rental—typically a 36-month term with set mileage limits. Whether you run daily errands around Plaza Del Valle or commute down Victory Boulevard, picking the right path depends on your driving volume and long-term goals.
| Feature | Financing a Honda | Leasing a Honda |
|---|---|---|
| Ownership | The lender transfers the vehicle title to your name once the loan balance reaches zero. | The leasing institution retains full ownership of the vehicle while you pay for its usage. |
| Monthly Payments | Generally higher because your payments go toward the entire purchase price of the car. | Typically lower, as you only finance the anticipated depreciation during the lease window. |
| Upfront Costs | A larger down payment is typically recommended to lower your overall financed amount and interest. | Usually requires just the first month’s payment, standard acquisition fees, and sometimes a security deposit. |
| Customization | Complete freedom to install aftermarket parts or modify your Civic or Accord as you see fit. | The vehicle must remain in its original factory condition without any permanent changes or accessories. |
| Mileage | No restrictions. Drive as much as you want across the San Fernando Valley and beyond. | Annual caps apply (e.g., 10,000 miles); overages often cost roughly 15 to 20 cents per extra mile. |
| Wear & Tear | Dings and scratches only affect what the car is worth when you eventually decide to sell. | Turn-in guidelines are strict; excessive interior damage or tire wear will result in penalty fees. |
| End of Term | You own the car outright. Enjoy driving payment-free, sell it, or trade it in. | Simply return the keys, purchase the vehicle for its residual value, or upgrade to a new lease. |
What Shapes Your Honda Financing and Lease Rates?
When you apply for an auto loan or lease, banks evaluate a blend of your financial health and the specific vehicle you're taking home. For families running daily errands down Van Nuys Boulevard or commuting on the 405, understanding these moving parts means you can lock in a structure that fits your reality. Ultimately, lenders look at your borrowing history alongside the price of the car to determine your rate.
- Your Credit Profile: A solid credit score generally opens the door to lower interest rates, significantly cutting the overall cost of borrowing.
- Upfront Down Payment: Cash at signing directly shrinks your loan balance. For instance, putting an extra $2,000 down upfront rather than rolling it into your financing immediately lowers your monthly obligation and reduces the total interest you'll pay.
- Term Length: Choosing a 72-month term instead of a 48-month term gives you a smaller monthly payment, but you'll pay more interest in the long run. Shorter terms require a higher monthly output but help you build equity much faster.
- Vehicle Type and Price: The MSRP of your chosen ride matters heavily. Lenders frequently feature promotional rates on select new vehicles, meaning the terms for a 2027 Honda Civic Hybrid might look a bit different than those for a larger gas-powered SUV.
- Debt-to-Income Ratio (DTI): Banks compare your existing monthly debts against your income. They just want to ensure that adding a new car payment won't stretch your budget too thin for everyday life around the San Fernando Valley, leaving you plenty of room for weekend trips to the Sherman Oaks Galleria.
What Special Honda Incentive Programs Can I Qualify For?
If you're looking to offset the cost of a new vehicle, tapping into targeted factory incentives is one of the smartest moves you can make. What this means for Van Nuys drivers is extra financial flexibility when securing a lease or loan for that daily commute down Victory Boulevard. Whether you're researching long-term vehicle value on sites like Edmunds or you're ready to sign the paperwork, Honda provides specialized financing programs designed to reward specific groups. For example, if you just wrapped up nursing school and secured a role at Kaiser Permanente Panorama City Medical Center, applying a graduate rebate to a highly efficient 2027 Honda Civic Hybrid puts you financially ahead of the curve before your first shift even begins.
- Honda College Graduate Program: Recent college grads can earn valuable factory rebates on new models. You'll just need to provide valid proof of your recent degree alongside current employment (or a firm commitment letter from a future employer) to unlock the savings.
- Honda Military Appreciation Offer: As a thank you to those who serve, eligible active-duty U.S. military personnel, veterans within a specific timeframe of separation, and their spouses can qualify for special incentives toward their next purchase or lease.
- Honda Loyalty Benefits: Already driving a Honda? Current owners often have access to exclusive loyalty offers when upgrading to select new vehicles, making it much easier to trade up from an older sedan into a spacious 2027 CR-V.
- Regional Valley Promotions: Manufacturer incentive packages shift throughout the year based on local market conditions. These area-specific offers routinely include specialized lease terms or attractive financing rates tailored directly for Southern California drivers.
How to Apply for Your Honda Lease or Financing

Securing the keys to a 2027 Honda Civic or CR-V Hybrid doesn't require a marathon of paperwork. The application process comes down to four basic stages: checking your borrowing power, bringing the right documentation, submitting a formal application, and finalizing your contract terms. What this means for Van Nuys drivers is a streamlined experience that respects your schedule—whether you're managing afternoon pickups near the Van Nuys Recreation Center or navigating heavy commuter traffic on the 405. Getting a head start online takes just a few minutes, which easily saves you an hour of desk time later when you’d probably rather be grabbing lunch at Plaza Del Valle. Here is exactly how to move from browsing to driving.
- Get Pre-Qualified: Start by viewing your estimated rates and borrowing limits through a soft credit pull. This step lets you build a realistic budget for your next vehicle without putting a ding on your current credit score.
- Gather Required Documents: Lenders need concrete proof to verify your identity and financial standing. You'll need to supply a valid driver's license, recent proof of income (like a pay stub or bank statement), verification of your current residence, and active auto insurance details.
- Complete the Formal Application: Moving forward with an exact car requires submitting a full application. This triggers a hard credit inquiry, allowing financial institutions to evaluate your comprehensive credit report and lock in your official annual percentage rate (APR).
- Review and Sign: In this final stage, you will confirm every detail of your agreement. This is the moment to verify your exact monthly payment, standard term length, and decide on optional protections—such as a Honda Care® plan, which is eligible for purchase on vehicles still within their original 3-year/36,000-mile Limited Vehicle Warranty window.
Should You Pay Cash or Finance Your Next Honda?
Buying a vehicle outright delivers immediate ownership and completely avoids the extra cost of interest charges. If you decide to purchase a versatile Honda CR-V, handing over the full amount upfront means you never have to worry about a monthly auto payment. For Van Nuys drivers, this approach frees up your month-to-month budget, making it easier to handle daily Valley living—whether that means covering housing costs or enjoying weekend outings near the Sherman Oaks Galleria. The main drawback is that sinking a massive portion of your liquid savings into a single purchase leaves a much smaller safety net for unexpected emergencies.
On the flip side, taking out an auto loan allows you to keep your bank account largely intact while securing a reliable ride. Choosing to finance a Honda Accord by putting down a standard 20% and spreading the remaining balance over 60 months will cost more in total interest over time, but it actively protects your emergency fund. This strategy keeps your cash accessible for other investments and life events, which is especially helpful when navigating a busy commute down Sepulveda Boulevard. Ultimately, the smartest route depends entirely on your personal comfort level with carrying monthly debt versus your desire to preserve upfront capital.
What Are the Pros and Cons of Each Payment Method?
Financing a vehicle builds long-term equity, making it ideal for high-mileage drivers, whereas leasing provides lower monthly payments and a new car every few years. What this means for Van Nuys drivers is you need to weigh your monthly budget against how much you travel across the San Fernando Valley. If you commute roughly 15 miles a day down Sepulveda Boulevard toward Sherman Oaks, a standard 10,000-mile-per-year lease covers your routine perfectly. Conversely, buying makes more sense if you frequently log heavy miles heading out to the San Gabriel Mountains on weekends.
Pros of Financing a Honda
- Total Ownership: Once you make that final payment, the vehicle is entirely yours. You can keep your 2027 Honda CR-V for a decade, sell it privately, or trade it in to upgrade later.
- No Mileage Caps: Drive as much as you want. Whether you're running daily errands to Panorama Mall or commuting across Southern California, you will never face end-of-term overage penalties.
- Complete Customization: Want to add genuine Honda roof rails to your Pilot for weekend getaways or upgrade the wheels? Buying gives you the freedom to modify your vehicle exactly how you like it.
- Building Equity: Every monthly payment increases your financial stake in the car. Over time, this creates tangible value that a lease simply doesn't offer.
Cons of Financing a Honda
- Higher Monthly Payments: Because you are paying for the entire purchase price of the vehicle over a set term, your monthly financial commitment is typically higher than if you were leasing.
- Long-Term Maintenance: After Honda's standard 3-year/36,000-mile Limited Vehicle Warranty expires, you become responsible for covering out-of-pocket repair costs as the car ages.
- Depreciation Risks: Like all vehicles, a financed car loses resale value over time, which means market fluctuations could affect what it is worth when you decide to sell.
Pros of Leasing a Honda
- Lower Monthly Costs: Leases only charge you for the vehicle's depreciation during your term. This often allows you to drive a higher-trim model—like a 2026 Honda Accord Hybrid Touring—for less money each month.
- Always Under Warranty: Most Honda lease terms last 36 months, which conveniently aligns with the 3-year/36,000-mile new vehicle warranty, so you rarely have to worry about major mechanical repair bills.
- Latest Technology: Upgrading every few years means you continually get access to Honda's newest driver-assist features, infotainment displays, and fuel-saving hybrid powertrains.
- Hassle-Free Returns: When the contract ends, simply bring the car back to the dealership. There is no need to haggle over trade-in values or find a private buyer.
Cons of Leasing a Honda
- Strict Mileage Limits: Standard contracts usually cap driving at 10,000 or 12,000 miles annually. If your daily commute along Ventura Boulevard suddenly gets longer, you could face per-mile fees at turn-in.
- Zero Equity: Since you are essentially renting the vehicle from the manufacturer, you do not own anything at the end of the contract, meaning you have no trade-in value to apply toward your next car.
- Wear and Tear Charges: While minor scuffs are expected, any significant damage from tight street parking around Van Nuys could result in extra reconditioning fees before you hand over the keys.
- Factory Condition Required: You cannot permanently modify a leased vehicle. It must be returned exactly as it was when it rolled off the lot.
How to Maximize Your Value When Shopping

Planning ahead changes the game when you are looking to bring home a new vehicle. For families running daily errands down Van Nuys Boulevard or commuters driving a fuel-efficient 2027 Honda Civic out toward Sherman Oaks, securing the right terms means more money stays in your pocket. That matters because establishing a solid budget and understanding exactly what goes into a modern auto contract keeps you in the driver’s seat from start to finish. Here is how mastering a few basic strategies helps you drive away with confidence.
- Review your credit early: Pull your report before stepping foot on a lot. Even a minor reporting error can bump you into a higher interest tier, so correcting mistakes well in advance gives you access to the most favorable borrowing rates.
- Gather outside quotes: Check with your local credit union or bank around the San Fernando Valley before you finalize your purchase. Having an external pre-approval acts as a strong baseline, and dealership financing teams can often match or beat those terms to earn your business.
- Watch the calendar: Automakers frequently launch fresh incentives near the end of a month, quarter, or when the next model year begins arriving. Timing your visit right can unlock promotional APRs or lease specials on highly sought-after models like the 2026 Honda Accord.
- Focus on the vehicle's price first: It is always tempting to start talking about monthly payments right away, but you’ll want to establish the total cost of the car beforehand. Treat the agreed purchase price and your trade-in valuation—which you can research through resources like Kelley Blue Book or Edmunds—as two completely separate negotiations.
- Know the loan terminology: If you are financing a spacious 2026 Honda Pilot for weekend trips up to the San Gabriel Mountains, pay close attention to the Annual Percentage Rate (APR), the total amount financed, and the loan term length. Remember, stretching a loan from 60 months to 72 months lowers your immediate monthly bill but increases the total interest you pay over the life of the loan.
- Demystify lease math: Leasing heavily depends on the capitalized cost (the vehicle's agreed value), the money factor (the leasing equivalent of an interest rate), and the residual value. High residual values—which mean the vehicle is projected to hold its worth well—typically translate directly to much lower monthly lease payments.
Frequently Asked Questions (FAQs)
What should I know about dealer add-ons at Honda Van Nuys?
Honda Van Nuys's certified specialists will provide clear, expert guidance on any optional features you might want for your San Fernando Valley commutes. Our team maintains the highest standards of transparency, ensuring you understand exactly what is included with your Honda Civic or CR-V before finalizing any paperwork.
How can I ensure transparency in pricing at Honda Van Nuys?
Backed by over 60 years of family-owned automotive experience, Honda Van Nuys’s team handles the pricing process with the highest standards of transparency. Our certified specialists walk families through every detail of the transaction so that buyers navigating busy routes like Victory Boulevard know exactly what they are paying for.
What are the common add-ons offered by Honda Van Nuys?
Our certified specialists offer clear, expert guidance on accessories that enhance your Honda Accord or Pilot for Greater Los Angeles driving. Honda Van Nuys's team reviews options that fit your lifestyle, whether you need practical cargo solutions for grocery runs to Panorama Mall or protective gear for the local climate.
How does Honda Van Nuys ensure a clear purchasing process without unexpected charges?
As part of the trusted Keyes Motors family, Honda Van Nuys delivers customer-first care and the highest standards of transparency during every sale. Our specialists review all costs side-by-side with eco-conscious drivers purchasing Honda hybrids to guarantee a straightforward experience free of surprises.
How does Honda Van Nuys support the local community?
Beyond automotive excellence, Honda Van Nuys demonstrates community trust through active support for local LA schools and regional charities. Our team also participates in an employee gift-matching program that invests directly back into the neighborhoods we serve across the San Fernando Valley.
What automotive experience does the team at Honda Van Nuys have?
The team at Honda Van Nuys brings over 60 years of family-owned automotive experience and unmatched brand expertise to every vehicle recommendation. As part of the Keyes Motors family—a recognized pillar in the automotive sector for over 75 years—our certified specialists deliver factory-trained technical precision for drivers all over the Greater Los Angeles area.
About Honda Van Nuys
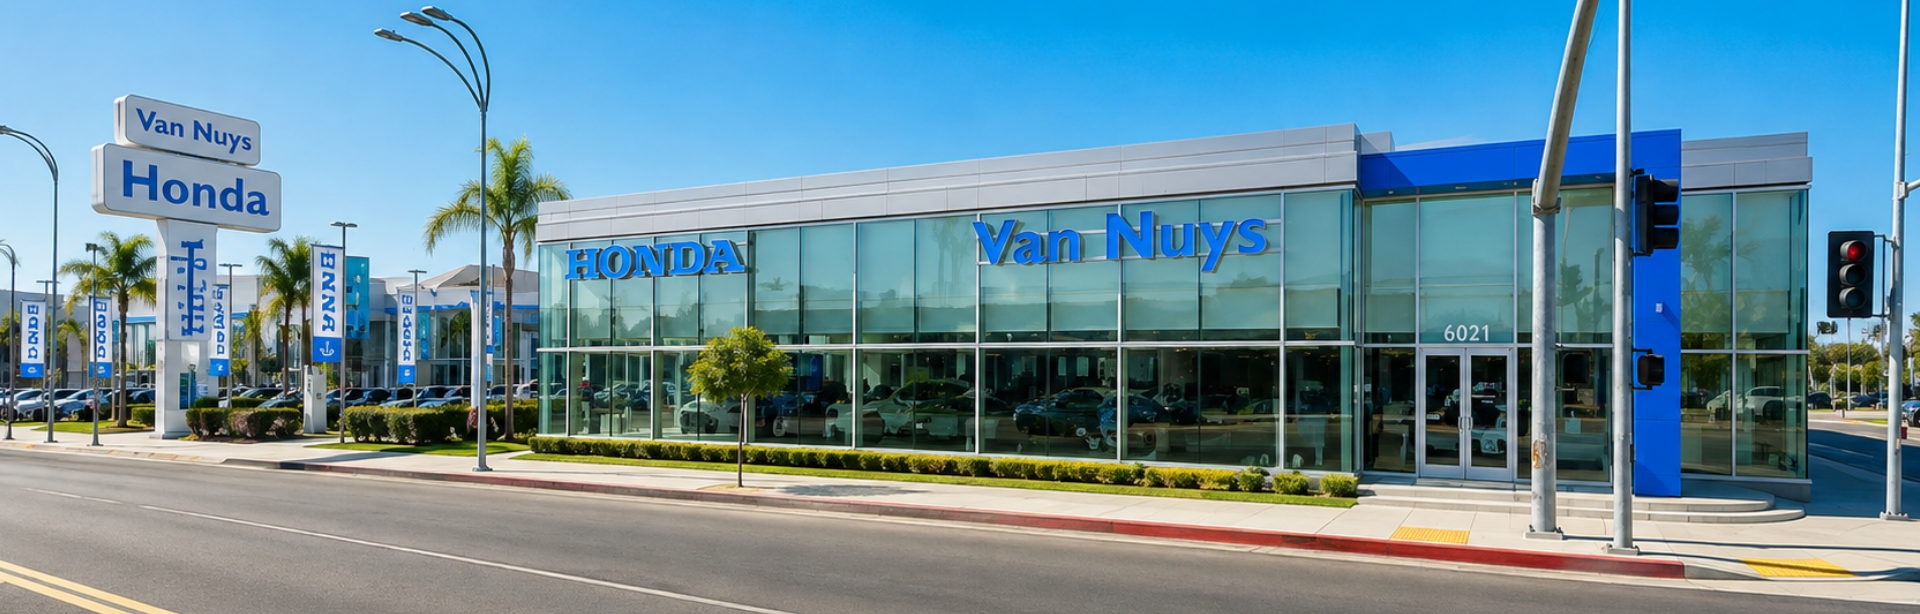
At Honda Van Nuys, we are proud to be the premier Honda dealership serving drivers across Van Nuys, the San Fernando Valley, and the Greater Los Angeles area. Backed by over 60 years of family-owned automotive experience, our team brings unmatched brand expertise and industry knowledge to every vehicle recommendation and service insight we share. As part of the trusted Keyes Motors familyâa recognized pillar of excellence in the automotive sector for over 75 yearsâwe maintain the highest standards of transparency, factory-trained technical precision, and customer-first care. Beyond automotive excellence, our commitment to topical leadership and community trust is demonstrated through our active support for local LA schools, regional charities, and a employee gift-matching program that invests directly back into the neighborhoods we serve. Whether you are seeking authoritative advice on Honda engineering or exploring the latest fuel-efficient models, our certified specialists are dedicated to providing clear, expert guidance you can rely on.
